There is no single roof age limit in Florida
People often ask how old a roof can be for insurance in Florida as if there were one statewide cutoff. There is not. What Florida has is a statute that limits when an insurer can use roof age alone as the reason to turn you down, plus each insurer's own underwriting rules layered on top.
The statute is section 627.7011(5), Florida Statutes. It was added by the Legislature in 2022 (the history note cites chapters 2022-268 and 2022-271, Laws of Florida) and applies to "homeowners' insurance policies issued or renewed on or after July 1, 2022."
This is general information, not legal or insurance advice. Your agent and your insurer can tell you how their rules apply to your house.
What section 627.7011 actually says
The roof-age subsection has four working parts.
Roofs under 15 years old. "An insurer may not refuse to issue or refuse to renew a homeowner's policy insuring a residential structure with a roof that is less than 15 years old solely because of the age of the roof."
Roofs 15 years or older. The insurer "must allow a homeowner to have a roof inspection performed by an authorized inspector at the homeowner's expense before requiring the replacement of the roof" as a condition of writing or renewing the policy. And if that inspection "indicates that the roof has 5 years or more of useful life remaining," the insurer may not refuse to issue or renew "solely because of roof age."
Who counts as an authorized inspector. The statute lists people "approved by the insurer" who are one of the following: a licensed home inspector, a certified building code inspector, a licensed general, building, residential or roofing contractor, a licensed professional engineer, a licensed architect, or anyone else the insurer recognizes as qualified to inspect a home.
How roof age is counted. Age runs from "the last date on which 100 percent of the roof's surface area was built or replaced." If the roof was replaced in sections over time, the clock starts on the date of the partial replacement that finished covering 100 percent of the surface.
What the statute does not do
Read the phrase "solely because of" carefully. The law stops an insurer from using age by itself as the reason. It does not require an insurer to cover a roof that is leaking, damaged or worn out, whatever its age. Subsection (6) also says the section does not apply to mobile home policies, and does not limit an insurer's ability to decline "for other lawful reasons."
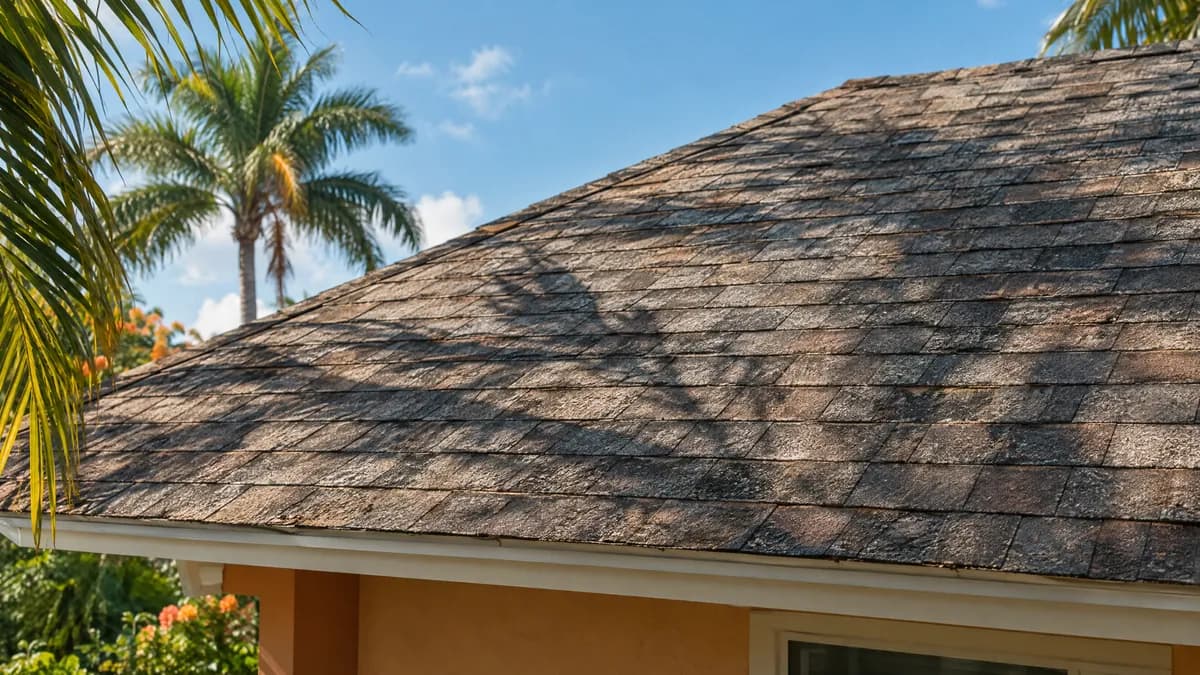
It also does not set a maximum age. A 30-year-old tile roof in good condition and a 16-year-old shingle roof with soft decking are both "15 years or older." What separates them is condition and remaining useful life, which is exactly what the inspection documents.
How one insurer applies it: Citizens
Citizens Property Insurance Corporation publishes its roof rules on its Inspections page. Roofs older than 25 years (shingle and similar "soft" coverings) or 50 years (tile, slate, clay, concrete or metal) "require documentation showing at least five years of remaining useful life." When a roof has less than five years left, the owner must show proof of a full replacement before a policy is written.
Citizens' own roof age FAQ states the same 25 and 50 year lines and notes that "some exceptions apply." One of those is for buyers: Citizens says a recent purchaser whose roof is damaged or has less than five years of life left may still qualify if the purchase happens within 45 days of the requested coverage date and a signed roofing contract shows a full replacement within 30 days of that date.
Other insurers set their own lines, and they change. If your roof is close to any threshold, ask your agent which carrier rule applies before you assume anything.
What "remaining useful life" means
Remaining useful life is the inspector's estimate of how many more years the roof covering can reasonably keep doing its job. Citizens describes it as "an estimate made by a trained professional" and says it relies on that professional to judge the roof's overall condition (Citizens FAQ).
It is not a formula. Two roofs installed the same year can have very different remaining lives depending on:
- the covering material and how it was installed,
- sun, salt air and wind exposure,
- past storm damage and repairs,
- how well flashing, valleys and penetrations have held up,
- ventilation and moisture in the attic below.
For a sense of scale, InterNACHI publishes an estimated life expectancy chart for Florida homes that lists 10 to 12 years for 3-tab asphalt shingles, 15 to 20 years for architectural shingles, 17 to 20 years for metal, and 80-plus years for clay or concrete tile. Those are typical ranges assuming normal maintenance, not promises about any one roof.
How the 4-point roof section documents age and condition
Most people meet these rules through the roof section of a 4-point inspection. On the current Citizens 4-Point Inspection Form (Insp4pt 03 25), the roof section asks the inspector to record, for both the predominant roof and any secondary roof:
- covering material,
- roof age in years,
- remaining useful life in years,
- date of the last roofing permit,
- date of the last update, and whether it was a full or partial replacement (with the percentage replaced),
- overall condition, satisfactory or unsatisfactory,
- visible damage or deterioration: cracking, cupping or curling, excessive granule loss, exposed asphalt, exposed felt, missing, loose or cracked tabs or tiles, soft spots in decking, and visible hail damage,
- visible signs of leaks, checked at the attic or underside of the decking and at interior ceilings.
The form says that with photos of each roof slope, this section "can take the place of the Roof Inspection Form." Citizens confirms that in its FAQ.
Note the secondary roof column. If part of the house has a different roof, such as a flat section over an addition, it gets its own entry, and Citizens says it expects "all roofs, both predominant and secondary" to be in acceptable condition (Citizens FAQ). A newer main roof does not carry an old flat section.
If you are also weighing whether you need a full inspection on top of the insurance paperwork, we cover that in how a 4-point compares with a full home inspection.
Why permit records matter
Because the statute counts age from the last date 100 percent of the roof was built or replaced, the most useful piece of evidence you can have is a closed roofing permit with a date on it. That is also why the form asks for the "date of last roofing permit" on its own line.
A permit record helps in three ways:
- It fixes the start date. Without it, age is estimated from what the inspector can see, and the seller's memory.
- It shows full versus partial. A repair permit for one slope does not reset the clock. The statute and the form both separate full from partial replacement.
- It covers the secondary roof. An addition or porch roof may have its own permit history.
Receipts and a roofer's warranty help too, but a permit is a public record the insurer can check. We explain where to look up permits in Manatee and Sarasota counties in our guide to getting your documents ready for a 4-point.
What to do next
If you are buying an older home, or renewing on one:
- Ask for the roof permit early. In a purchase, ask the listing agent for the permit number or the roofer's invoice as soon as you are under contract.
- Book the insurance inspection inside your inspection period. That leaves time to get quotes, or to negotiate a roof replacement, before you are committed.
- Ask your agent about the carrier's roof rule. The statute sets a floor. Carriers such as Citizens publish their own age lines, and others may differ.
- Fix active leaks before you apply. Citizens says serious hazards, including active leaks, should be repaired before an application is submitted.
High Tide's 4-point insurance inspection documents the roof's covering, age and condition with photos, and Joanna holds InterNACHI's Roof Inspector certification. It takes about 45 minutes to an hour on site and costs $175 on its own, or $125 when added to a home inspection. The inspector documents what is there. Your insurer decides what it will write.